Cost Is Not the Same as Value
A project can finish on time, come in under budget, pass every gate, and leave the organisation measurably worse off. It happens most often through a series of small, defensible decisions in which the cheaper compliant option was selected, each one saving money the project could see and costing money the project could not.
Cost is what the work consumes, measured while the project is running, by the people running it. Value is what the result is worth to whoever uses it, collected over years, usually by somebody else. Section 2.4.1 of the PMBOK® Guide Eighth Edition opens the finance material with that broader framing, and the practical consequence is that a project manager optimising only the number they are held to will systematically damage the number they are not.
Three ways a cost decision destroys value
Whole-life cost. The purchase price is a fraction of what an asset costs over its life, and energy, consumables, maintenance intervals and spares availability usually dominate. A pump that is four per cent cheaper and eleven per cent less efficient is a poor deal by the end of the second year, and the arithmetic to show that takes about twenty minutes.
Risk moved to somebody else. Removing a redundant feed, a standby unit or a spares holding saves money in the project and places an exposure on operations, who will carry it for a decade. That transfer is legitimate where it has been decided deliberately by somebody who owns both sides. It is destructive when it happens as a value engineering exercise conducted against a capital number alone.
Capability quietly foregone. The option that gets cut is frequently the one that would have allowed something later: the spare capacity, the second interface, the space left in the panel. None of it is required today, which is why it is easy to remove, and its absence sets the cost of the next project three years out.
Why the cheap option keeps winning
The budgets are different budgets. A saving lands in a capital account this year and the consequence lands in an operating account every year afterwards, and in most organisations those are held by different people with different incentives. Nobody has to behave badly for the wrong answer to emerge; the structure produces it.
The decision happens before the evidence. Selection decisions are usually taken early, when the operating data that would settle them does not exist yet, and under time pressure that makes the simplest comparison the attractive one. Price is available immediately. Whole-life cost requires somebody to go and work it out, and if nobody asks for it in the week the decision is being made, it is not there when it is needed.
A pump, four per cent, and eleven years
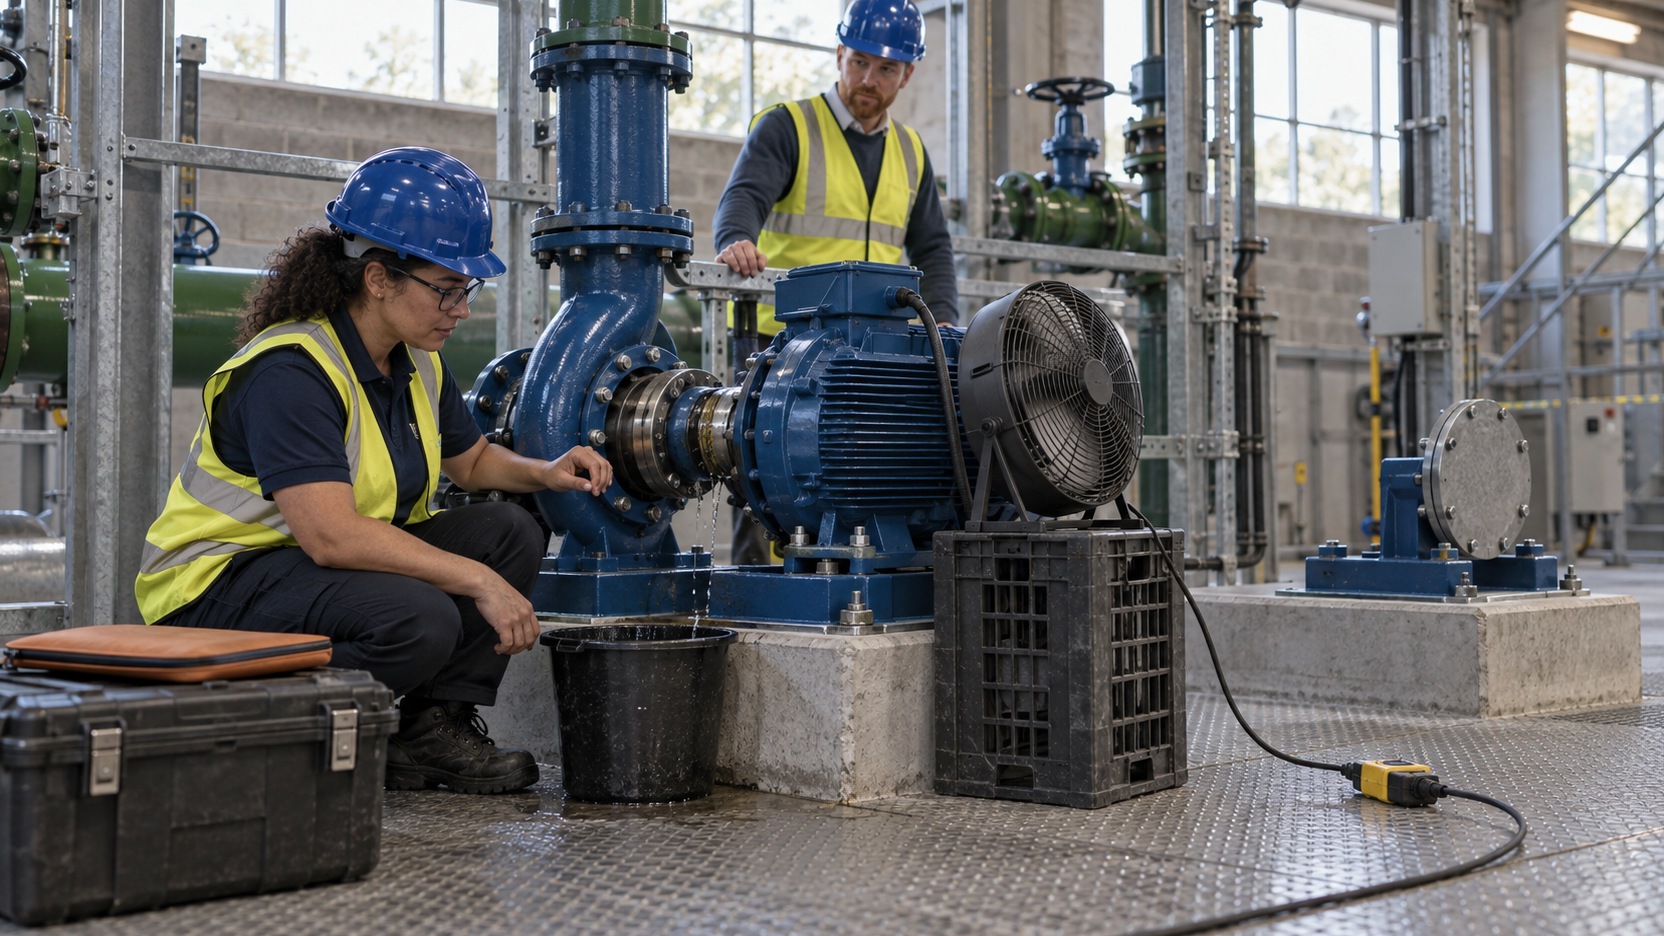
A water company was replacing duty pumps at a treatment works as part of a wider refurbishment. Two units met the specification. One was about four per cent cheaper on capital; the other was quieter, ran cooler, and carried a meaningfully better efficiency figure at the duty point the works actually operated at, which was not the point on the datasheet.
The cheaper unit was selected, correctly under the rules in force: it met the specification, it was compliant, and the capital budget was under pressure. Nothing improper happened at any stage.
The unit ran hot in the plant room, which was warmer than the design assumption because a ventilation change had been value engineered out of a different project two years earlier. Operations put a portable fan on it within a month and it stayed there for eleven years. The gland needed attention at roughly twice the expected interval, which was a half-day visit every eight weeks for a maintenance team already stretched. The energy difference alone, at the duty the works ran, came to more than the original capital saving inside three years.
None of this appeared anywhere in the project's reporting. The project closed under budget and was regarded as a good one. The costs went to operations, in a different budget, attributed to an asset rather than to a decision, and the connection between the two was never made by anybody with an interest in making it.
What changed the pattern was procedural and small. The company introduced a requirement that any selection where the options differed by more than a stated margin in energy or maintenance had to carry a whole-life comparison, signed by both the project and the asset owner. The comparison was one page. In the following two years it reversed about one selection in five, and in a few cases it confirmed the cheaper option with a proper basis, which was equally useful.
Making value visible in the decision
Put a number on what the operator will pay. Whole-life cost is not an exotic technique: energy at the real duty, maintenance hours at the real interval, spares, and the disposal position, over a stated period. It does not need to be precise to change a decision, and a rough figure in the room beats an accurate one produced afterwards.
Name who holds the benefit and who holds the cost. Where those are different people, both should be in the decision, and where they cannot be, the position of the absent one should be represented by somebody with the mandate to say no. A decision made only by the party holding the capital budget is structurally biased, and naming that in a meeting is easier than repairing the result.
Record the basis, not just the choice. A one-line note saying which option was selected, on what comparison, and what was assumed about operating conditions makes the decision auditable later. It is also the only thing that allows an organisation to learn that its assumptions about plant room temperature, or duty points, or maintenance access, are systematically optimistic.
For a PMP® candidate, it helps to recognise that a project is accountable for value and not only for cost, so a scenario offering a cheaper compliant option is asking what happens after handover. A response that takes the saving without establishing the whole-life position has optimised the visible number. Decisions where the cheapest option is fully compliant and clearly wrong are the kind a structured PMP exam preparation course puts up for examination.
The question to carry into the next decision is short. For the next significant selection decision you make, ask who pays for it after handover, and whether that person has seen the comparison. If the answer to the second half is no, the decision is being taken with half the information, and obtaining the other half is usually a morning's work.
Interested in going further?
Defending a cheaper option is easy at the time and expensive for a decade, and the people who pay are rarely in the room when it is chosen. Omega's PMP® Exam Preparation works through decisions where cost, value and accountability sit in different places.
Value, cost and the relationship between them run through the PMBOK® Guide Eighth Edition.
Ad · Amazon affiliate link.
References
A130: Sunk Cost: The Money You Should Stop Defending
A203: How to Handle Competing Constraints in a PMP Scenario
A125: Budget vs Cost Baseline vs Funding
A047: Sustainability vs Cost: How Should a Project Manager Decide?
A014: Intended Value vs Realised Value
PMP and PMBOK are registered marks of the Project Management Institute, Inc.