Budget vs Cost Baseline vs Funding
A project can be inside its approved budget, tracking accurately against its baseline, and unable to pay an invoice in November. Those three statements are compatible, and the reason is that budget, baseline and funding are three different things that everybody calls the money.
Section 2.4 of the PMBOK® Guide Eighth Edition brings the financial material together under one domain, and the distinctions below are worth holding precisely, because each of the three fails in a way the other two cannot warn you about.
Three different numbers
The cost baseline is what performance is measured against. Estimates for the work, aggregated and spread across time, with contingency for identified risks included. It has a shape: so much in each month or quarter, following the actual profile of the work. Management reserve sits outside it, because the baseline is what the project undertakes to perform within.
The budget is the total authorised. The cost baseline plus the management reserve held above it. It is the number quoted in approvals and the number people mean when they say the project is a four million pound project, and it is the least useful of the three for managing anything, because it has no shape and no timing.
Funding is money actually available to spend, and when. Organisations release money in tranches, against financial years, at gateways, or subject to limits per period. Funding follows the organisation's rules; the baseline follows the work; and where those two profiles differ, the project has a problem that neither the budget nor the baseline will reveal.
Why the funding profile bites
Timing and limits. A baseline that needs sixty per cent of its spend in the first five months, against funding released evenly across four quarters, will stop the work in month four however correct the total is. This is a planning problem with a simple fix if it is spotted early, and an expensive one if it is spotted when a supplier's invoice cannot be paid.
Financial year boundaries. Money that does not get spent in the year it was allocated frequently cannot be carried, and money planned for next year rarely arrives early. This produces two familiar distortions: a scramble to commit spend in the final quarter, and work deferred across a boundary for reasons that have nothing to do with the project.
A migration inside its budget with no money
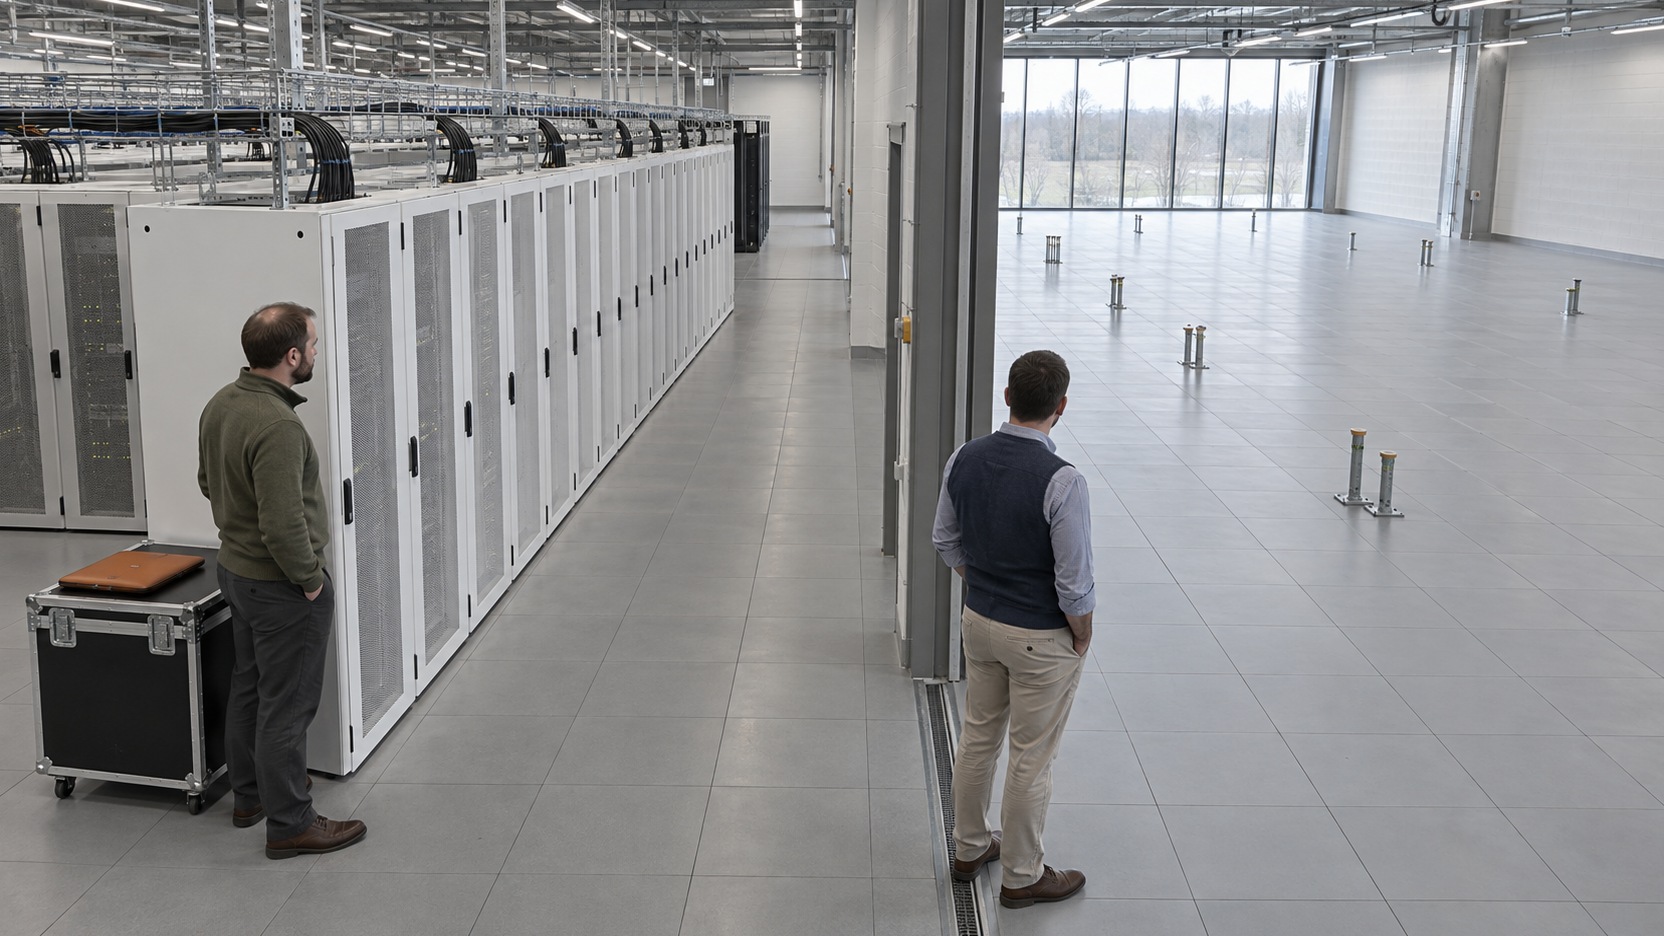
An IT services provider was migrating a client's estate into a new data hall, with capital approved at about four and a half million pounds across two financial years. The cost baseline was properly built: heavy in the first eight months, when the hall fit-out, cabinets, power distribution and cabling all landed, then much lighter through the migration itself.
Capital was released by the client's finance function in equal quarterly tranches, which is how that organisation released all capital, and nobody had compared the two profiles. The mismatch was visible from the start to anybody who laid them on the same page, which happened in month seven, when the fit-out contractor's third invoice could not be paid.
The project was inside budget. Spend was tracking the baseline almost exactly. And there was no money available until the following quarter, so the fit-out paused for five weeks with a fully mobilised contractor on site, who charged for the standing time, which was the first genuinely wasted money in the programme.
The recovery was a conversation with the client's finance director that should have happened in month one. Two tranches were brought forward against a revised profile, and the second hall, which had been planned for the following year, was deferred deliberately rather than by accident, which left an empty shell beside the built row for about eight months.
What the provider added to its own process was one page: the baseline profile and the funding profile on the same chart, produced at approval and reviewed monthly. On the next three programmes it caught two mismatches, both fixable with a phone call at the point where a phone call was enough.
Keeping the three aligned
Plot the two profiles together from the start. Cumulative baseline spend against cumulative funding available, on one chart. Where the first crosses above the second at any point, the project will stop there, and knowing the month is what allows the conversation to happen while options exist.
Report against the baseline, not the total. Spend against the authorised total is nearly meaningless mid-project, because it compares an amount with no timing to a point in time. Spend against the time-phased baseline is the comparison that tells you something, and it is the basis of every useful forecast.
Say which number you mean. In meetings the word budget covers all three, and a reasonable conversation can run for twenty minutes with two people using the same word for different things. Naming the number, briefly, costs a few words and prevents a class of misunderstanding that is hard to unpick later.
For a PMP® candidate, it helps to recognise that the three are distinguished by scope, timing and availability, so a scenario about a project unable to proceed despite being within budget is describing a funding constraint. A response that reviews the estimates addresses a number that was never the problem. Situations where the money is authorised and not available are a standing feature of a structured PMP exam preparation course.
Ask your finance contact one question this week: in what amounts and at what dates does our money actually become available? Put their answer beside your spend profile. Most projects have never done this, and a surprising number find a crossing point they did not know about.
Interested in going further?
Financial trouble on projects is more often about timing than about totals, and timing is invisible in the number everybody quotes. Omega's PMP® Exam Preparation works through project finance as profiles rather than headline figures.
Budgets, baselines and funding are treated together in the PMBOK® Guide Eighth Edition.
Ad · Amazon affiliate link.
References
A123: The PMBOK 8 Finance Performance Domain: What It Really Covers
A124: Cost Is Not the Same as Value
A105: Scope Baseline Explained
A203: How to Handle Competing Constraints in a PMP Scenario
A129: Estimate at Completion: What Question Are You Really Answering?
PMP and PMBOK are registered marks of the Project Management Institute, Inc.