The PMBOK 8 Finance Performance Domain: What It Really Covers
The change of word matters. Cost control asks a narrow and answerable question: is the project spending what it planned to spend? Finance asks where the money comes from and when, what it is buying, whether the purchase is still worth making, and who decides. A project manager can answer the first question perfectly every month and still be running something that is quietly a poor use of the organisation's money.
Section 2.4 of the PMBOK® Guide Eighth Edition gathers this material under the Finance Performance Domain, and the breadth is deliberate. Cost control sits inside it as one concern among several.
Cost is one question inside finance
Cost control is about adherence. Estimates, a baseline, actuals, variances, forecasts. It is measurable, it is reportable, and it is what most project managers are held to.
Finance is about the money as a whole. Funding availability and timing, the value the spend is buying, the decision to continue or stop, and the governance around all of it. These questions are less frequently asked of a project manager and they are the ones that determine whether the project was worth running.
What the broader frame adds
Funding, and when it arrives. Approved money is not available money, and a project can be within budget and unable to pay an invoice in November because of how tranches are released. This belongs to the project manager, because nobody else will notice the mismatch in time.
Financial decisions, including stopping. Whether to continue, whether to buy or build, whether to accept a supplier's proposal, whether a sunk cost is influencing a judgement it should not. Money already spent is gone whatever happens next, and the only question is what the remaining spend buys.
Value, not only expenditure. Whole-life cost, the operating consequence of a capital decision, what the organisation gets for the money over the asset's life. Cost reporting is silent on all of it, and the silence favours the cheaper option every time.
Governance around the money. Who can authorise what, what reserves exist and who releases them, what has to be reported and to whom. A project manager who understands the financial governance of their organisation can move considerably faster than one who discovers each threshold by crossing it.
Spares for equipment that was replaced
An oil terminal ran a major turnaround, and the project managed its cost impeccably: weekly cost reporting, disciplined change control, a final account within one per cent of budget.
Early in the planning, a decision was taken to buy a set of custom spare parts for two pumps, at a cost of about ninety thousand pounds, to protect the turnaround against a long lead time if either failed during the outage. That was a reasonable schedule-protection decision and it was recorded as such.
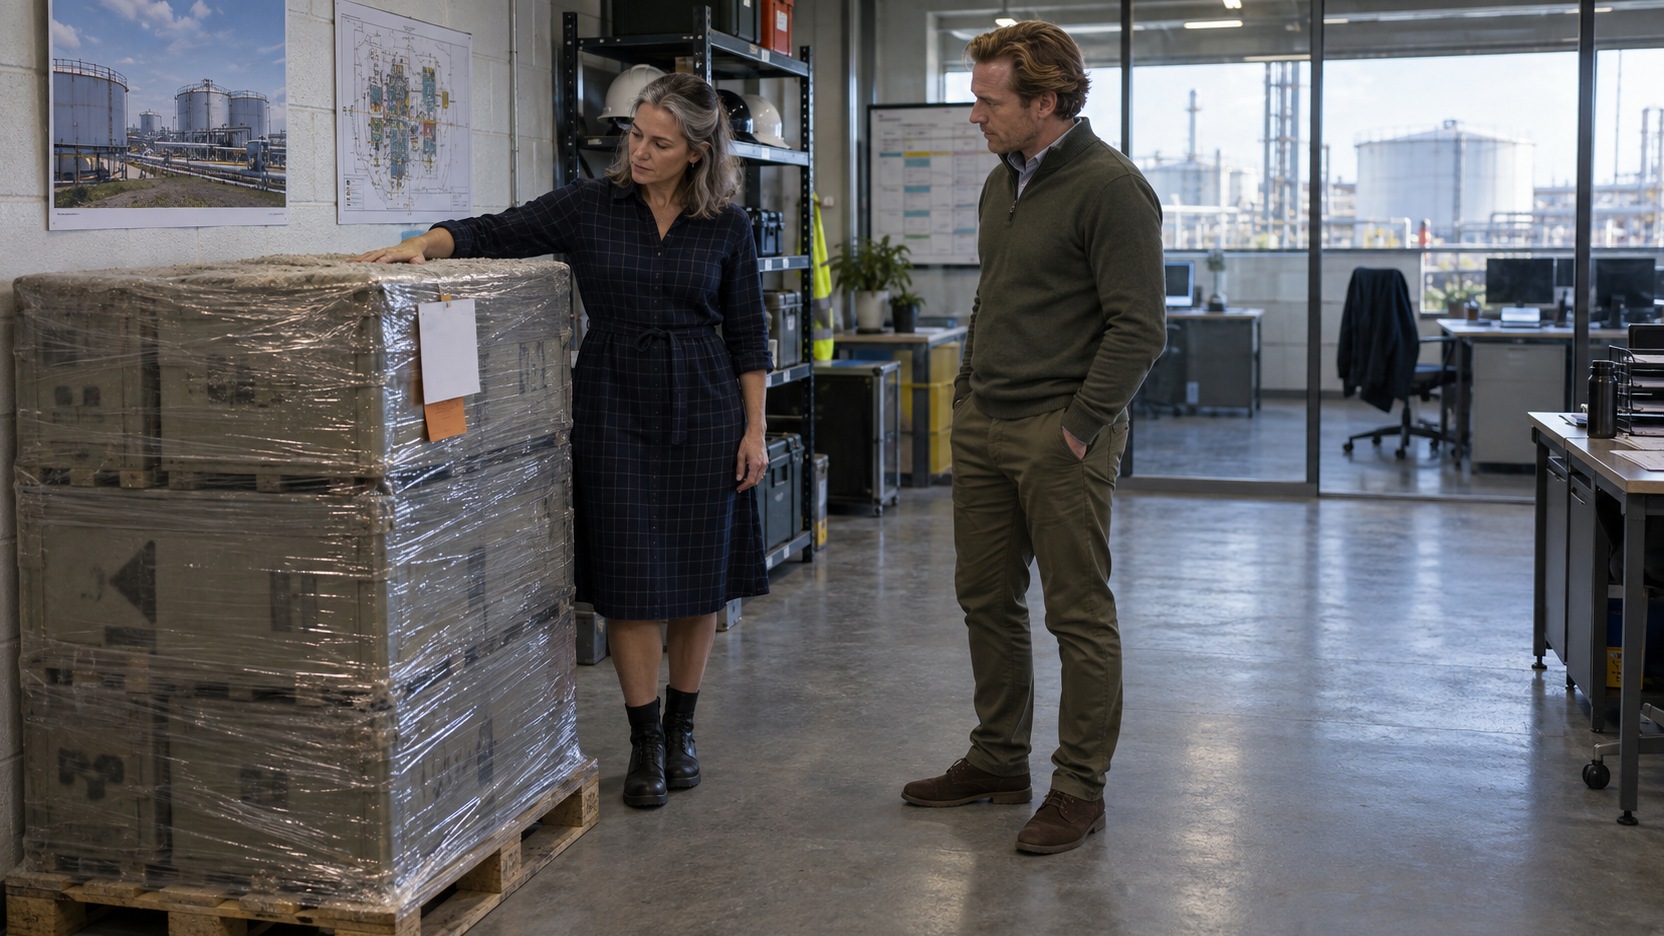
Three months later, the scope changed: both pumps were replaced entirely with a different model, approved and funded through the proper route. The spares had been ordered and could not be returned. They arrived, were placed against the wall of the planning office, and stayed there, shrink-wrapped and stencilled for equipment that was no longer installed.
Nothing in the cost reporting registered a problem. The spares were within budget, the change was within budget, and the final account was excellent. What had happened was a financial decision, taken correctly at the time, that nobody revisited when the basis for it disappeared, and no report the project produced was capable of asking the question.
The terminal's change process gained one line afterwards: any change that invalidates a previous commitment must state what happens to that commitment. On the next turnaround it caught two orders, one of which was cancelled inside the supplier's notice period.
What this changes for a project manager
Ask what the money is buying, not only whether it matches the plan. The second question is your report; the first is your job. A commitment made for a reason that has since evaporated is worth raising even when it is entirely within budget.
Learn your organisation's financial machinery. Where reserves sit, who releases them, how funding is profiled, what thresholds apply. A morning with a finance business partner at the start of a project saves several difficult weeks later and is almost never done.
For a PMP® candidate, the practical reading is that the domain covers funding, value and financial decisions alongside cost control, so a scenario about a project comfortably within budget may still contain a financial problem. A response that reports adherence has answered the narrowest available question. A structured PMP exam preparation course works on situations where the cost position is sound and the money is being poorly used.
Look at the three largest commitments your project has made and check whether the reason for each still holds. Anything ordered for a purpose that has since changed is worth a conversation with procurement today, because notice periods are the only thing that decides whether that conversation is free.
Interested in going further?
Budget adherence is the easiest financial question to answer and the least interesting one about a project. Omega's PMP® Exam Preparation works through project finance as funding, value and decisions.
The Finance Performance Domain is set out in full in the PMBOK® Guide Eighth Edition.
Ad · Amazon affiliate link.
References
A125: Budget vs Cost Baseline vs Funding
A129: Estimate at Completion: What Question Are You Really Answering?
A128: Do You Still Need to Memorise EVM Formulas for PMP?
A127: CPI and SPI Explained Without Formula Memorisation
A132: The PMBOK 8 Stakeholders Performance Domain: What It Really Covers
PMP and PMBOK are registered marks of the Project Management Institute, Inc.