Contingency Reserve vs Management Reserve
Most projects carry money that is not allocated to any particular piece of work. On a well-run project that money comes in two kinds, held in different places, released by different people, and the distinction between them is doing real work. On a project where it has all been merged into one pot labelled contingency, the distinction is still there. It has simply become invisible, which means nobody can tell whether the project is absorbing the trouble it planned for or the trouble it did not.
Contingency reserve covers identified risks: the things on the risk register, with owners and estimates against them. Management reserve covers what nobody identified, and it belongs to the organisation rather than to the project. The Finance Performance Domain of the PMBOK® Guide Eighth Edition, at Section 2.4, treats reserves as part of how a project is funded and governed, which is the useful frame, because the difference between the two is mostly a difference in who decides.
Two different questions
Contingency answers a question the project has already asked. A risk was identified, assessed and priced, and the money sits ready for the day it happens. The ground investigation suggested a chance of running into made ground; the supplier's lead time carries a known exposure; the integration with the legacy system might need a second round. Each of those has a number against it, and contingency is the sum of the numbers, adjusted for the fact that they will not all happen at once.
Management reserve answers a question nobody asked, because nobody knew to ask it. Whatever turns up that was genuinely outside the envelope the project was authorised against belongs here. Its size is a judgement about the class of project rather than an arithmetic exercise: a first-of-a-kind facility in an old building justifies more than the twelfth iteration of a familiar rollout, and both figures come from the organisation's appetite for surprise, not from the risk register.
Where the money sits and who releases it
Position in the budget. Contingency sits inside the cost baseline, because the project expects to spend it and is measured with it included. Management reserve sits outside the baseline, in the authorised funding but not in the number the project is performing against. That placement is the reason a management reserve drawdown is a formal event: it moves money across the baseline boundary and the baseline changes.
Authority to release. The project manager draws on contingency, within whatever thresholds the project's governance sets, and does so as part of managing the project. Management reserve is released by the sponsor or a governance body, on a case put by the project. Where a project manager can quietly draw on both, there is one reserve with two names, and the organisation has lost its early warning.
What a drawdown tells you. This is the part that gets overlooked and it is worth more than either of the others. A project consuming contingency at the rate it expected is behaving as designed, however uncomfortable the individual events feel. A project reaching for management reserve is telling its sponsor that the situation contains something the plan did not contemplate, and that is information the sponsor needs on the day it happens, not at the next quarterly review. Merging the two removes the signal entirely, and the first anybody knows is a funding request with no story attached.
A laboratory refurbishment and a ceiling nobody had opened
A university was refurbishing three teaching laboratories in a nineteen-sixties science building over a summer vacation. The budget carried about eleven per cent contingency against a risk register with the usual entries: asbestos in the floor screed, which the survey had flagged as likely, extract capacity for the new fume cupboards, and the risk of the specialist bench supplier slipping.
Two of those happened. The screed came up positive in two of the three rooms and the removal cost about sixty per cent of the contingency across four weeks. That was uncomfortable and it was entirely correct: a risk was identified, priced, and it occurred, and the money did exactly what it had been set aside to do. Nobody needed to escalate anything.
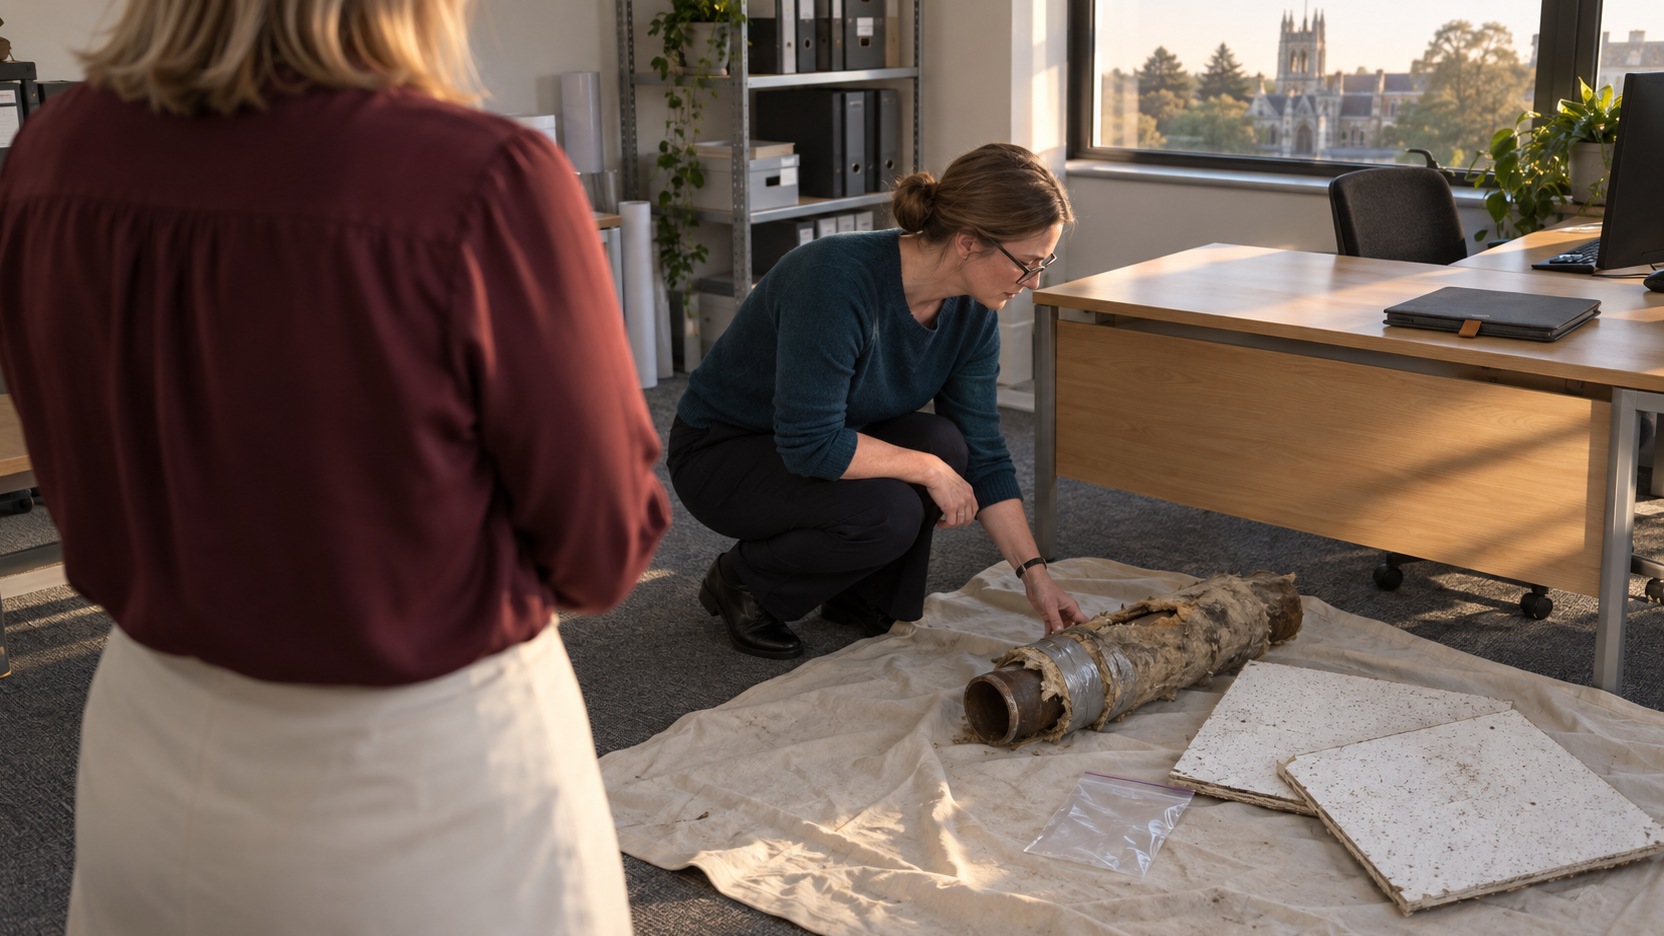
The third event was different. Opening the ceiling void in the end laboratory revealed a live gas line serving a building two doors away, running through the void at a shallow depth, appearing on no drawing anyone could produce and unknown to the estates team. It could not be worked around, it could not be isolated during term time, and the diversion took nine weeks and a sum comparable to the whole of the original contingency.
The project manager's first instinct was to take it from what remained of contingency and carry on, and that instinct is the one worth examining, because it would have looked like control. It would also have concealed the fact that the project had encountered something outside its authorised envelope, and by October the university would have had a room short of a laboratory and a budget overrun with no explanation attached to it.
What happened instead took a day. The case went to the estates committee as a management reserve request with the survey history attached, and it came back approved with a decision the project could not have taken alone: one laboratory would open a term late, the other two would open on time, and the timetable would be rebuilt around it. The reserve paid for the diversion. The committee also commissioned a void survey across the rest of the building, which found two more undocumented services and changed the scope of the following year's programme.
Keeping them apart in practice
The practical arrangement is unglamorous. Hold the two in separate lines, with contingency attached line by line to the risks that justify it, and review the drawdown against the register monthly so that the burn rate means something. When something arrives that is not on the register, the first question is whether it is genuinely outside what the project was authorised for, and that question is answered honestly and in front of the sponsor.
The temptation runs the other way in both directions. Project managers who dislike escalation will stretch contingency to cover the unforeseen, and organisations that dislike releasing reserve will push projects to absorb it. Both behaviours produce the same outcome: the funding decision is taken by whoever has the money rather than by whoever holds the accountability for the project's objectives.
For a PMP® candidate, what helps is seeing that the two reserves are separated by decision rights, so the question to ask of any funding situation is whose decision this is. A situation where a project manager can spend either pot without reference to anybody is describing a governance gap. Funding situations where the sum is affordable and the authority is the real issue come up repeatedly in a structured PMP exam preparation course.
The check takes an afternoon. Find out how much of your contingency remains, which identified risks it is still standing behind, and who in the organisation is able to approve money beyond it. If the answer to the last part is unclear, that is a conversation to have before something arrives out of a ceiling void, because the answer becomes very much harder to obtain once there is an urgent invoice attached to it.
Interested in going further?
Reserves are one of the few places where a project's funding and its governance are the same conversation, and drawing on the wrong one hides exactly the information a sponsor needs. Omega's PMP® Exam Preparation works through funding decisions where the authority matters more than the amount.
Reserves, budgets and funding are covered together in the PMBOK® Guide Eighth Edition.
Ad · Amazon affiliate link.
References
A123: The PMBOK 8 Finance Performance Domain: What It Really Covers
A129: Estimate at Completion: What Question Are You Really Answering?
A125: Budget vs Cost Baseline vs Funding
A128: Do You Still Need to Memorise EVM Formulas for PMP?
A127: CPI and SPI Explained Without Formula Memorisation
PMP and PMBOK are registered marks of the Project Management Institute, Inc.