Expected Monetary Value Explained
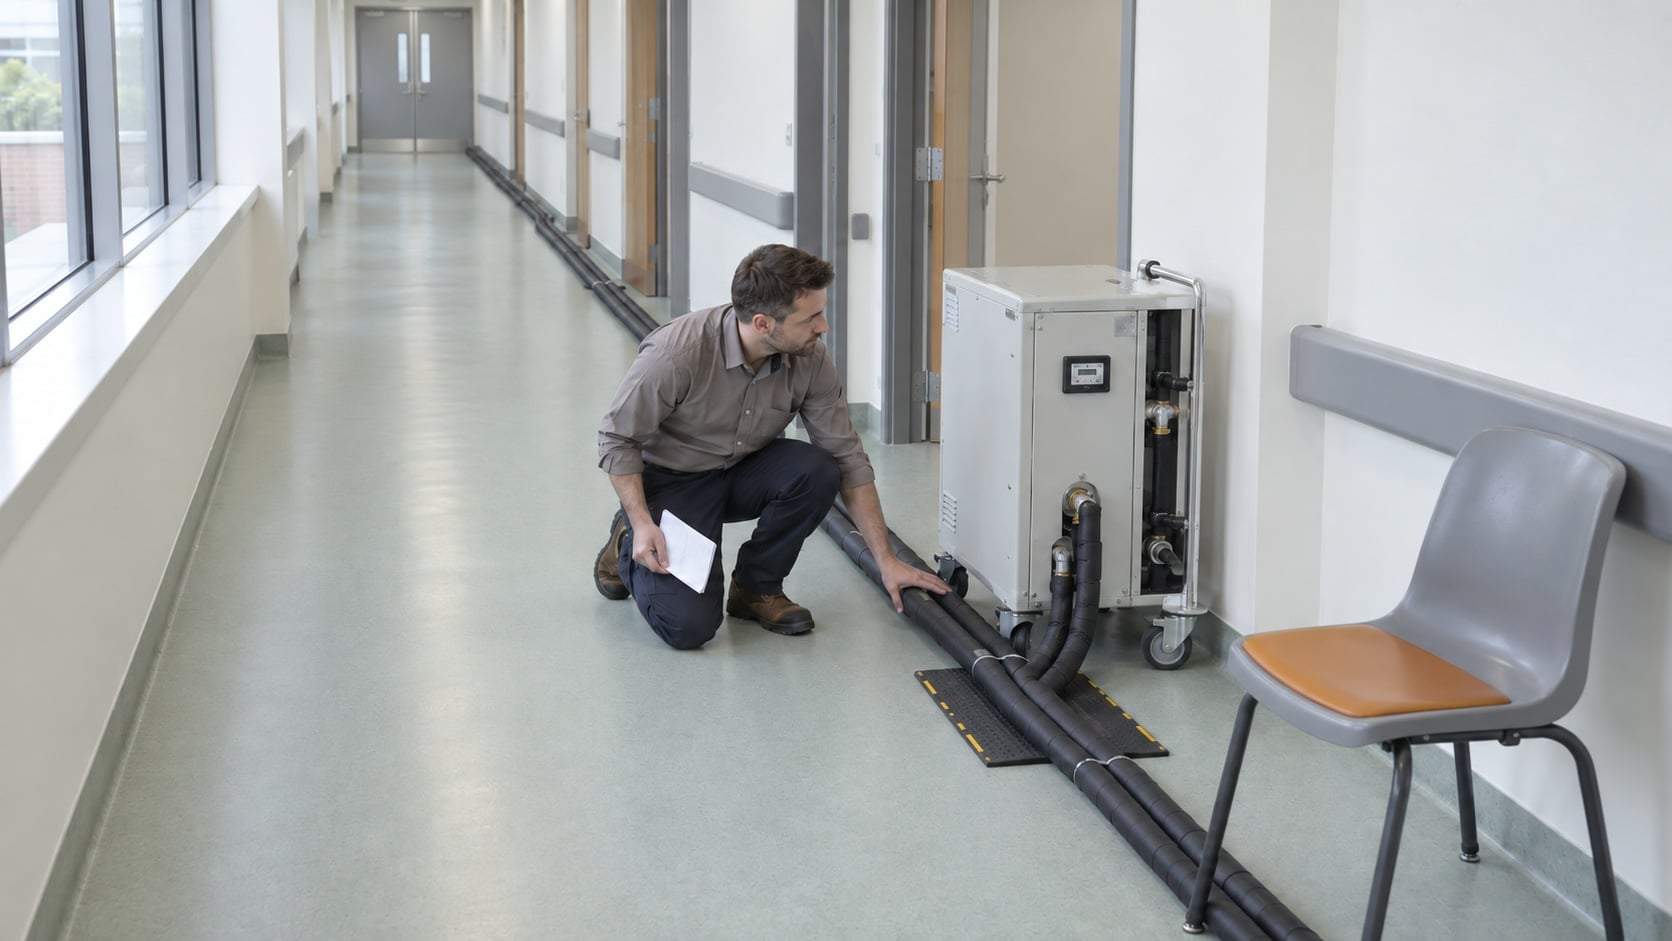
A sponsor asks a fair question. The team wants £42,000 for temporary heating plant that may never be needed. The existing boilers might well survive the fourteen weeks of the works, and if they do, the money has bought nothing anyone can point at. Someone in the room says the chance of failure is only about one in four. Someone else says one in four is high enough to lose sleep over. Both statements are reasonable, and neither of them settles anything.
Expected monetary value is the arithmetic that makes that argument comparable. Multiply the probability of an outcome by its financial impact, then add the results across the outcomes you are considering. A 25% chance of a £180,000 problem carries an expected monetary value of £45,000. Set beside a certain £42,000, the two options are close, and the closeness is itself worth knowing, because it tells you the decision will not be won by better arithmetic.
The convention is simple. Threats are expressed as negative values and opportunities as positive ones, so a decision option with several possible outcomes can be summed into a single figure. Where a decision branches, the same calculation is usually laid out as a decision tree, but the underlying method does not change. EMV appears among the tools and techniques gathered in Section 5 of the PMBOK® Guide Eighth Edition, presented as an aid to project decisions rather than a step every project is expected to perform.
The word doing the most work in the definition is "expected", and it does not mean "likely". It means the average across many repetitions. That single point governs almost everything useful about the technique.
When the average is the right thing to look at
EMV earns its place when you are comparing options that differ in both cost and likelihood, and when the comparison is otherwise being made by assertion. Buying certainty is the classic case: standby plant, a second supplier, extra testing, an insurance-style arrangement, a longer float. Each of these converts an uncertain cost into a known one, and EMV is the only straightforward way to ask whether the price of that conversion is sensible.
It is also reasonable as one input to contingency sizing. Averaging is more defensible across a register of many independent risks than it is for any single one, because over enough events the highs and lows have some chance to offset each other. That is the situation the mathematics was designed for.
Opportunities deserve the same treatment and rarely get it. An early completion incentive worth £90,000 with a 40% chance of being earned carries an expected value of £36,000, which is a perfectly respectable basis for deciding how much acceleration effort to fund.
The technique fits badly in three situations. The first is a single event whose worst case the organisation cannot absorb, where the average is irrelevant because you will only ever experience one outcome. The second is an impact that resists honest monetisation, such as clinical disruption, safety, regulatory standing or public confidence; you can attach a number, but you should say plainly that you have done so and on what basis. The third is a probability nobody can defend. If the 25% came from a shrug, multiplying it by a precise-looking impact produces a figure with far more authority than the input deserves.
There is also a proportionality question. Plenty of risks are resolved perfectly well by qualitative screening and a short conversation. Quantitative analysis costs time and attention, and it should be reserved for decisions where the money is real and the choice is genuinely unclear.
£42,000 now against £45,000 on average
Take the heating example properly. A phased plant replacement runs through an occupied hospital wing over fourteen weeks. Option A hires temporary boilers at £3,000 a week, a known £42,000. Option B runs on the existing plant and accepts the risk. If it fails during the works, the estates team estimates £180,000 to cover an emergency hire at short notice, a partial ward decant, agency cover and a standstill on the works themselves. At a 25% probability, the expected monetary value of Option B is £45,000.
On the numbers, Option A wins by £3,000, which is well inside the noise. So test the inputs rather than the answer. At 15% probability the expected value of doing nothing falls to £27,000 and Option B looks clearly cheaper. At 35% it rises to £63,000 and Option A looks obvious. The whole decision therefore rests on a probability estimate that has moved the answer twice, which tells the project manager exactly where the next hour should go: into the boiler service history, the age and failure record of comparable units, and whether the works themselves raise the load or the risk of a trip.
Two other things usually emerge once the figures are on the table. One is that the £180,000 is a range rather than a number, and the low end may not justify anything while the high end justifies everything. The other is that a third option often appears. Hiring temporary plant for the six coldest weeks only, at £18,000, covers the period when a failure would be both more likely and more damaging, and leaves the milder weeks exposed at a much lower cost. EMV thinking is at its best when it improves the options rather than merely ranking the two already on offer.
What the number never says
No single event will ever cost £45,000. It will cost nothing or it will cost £180,000. An expected value is a comparison currency, not a prediction, and the most common way to misuse it is to quote it as though it were the amount that will appear in next quarter's figures.
The same caution applies to a register total. Summing the expected values of forty risks does not produce a sum that will be spent, and it can mislead in both directions. Risks that share a cause do not behave independently, so a single trigger can convert several of them at once. A register also only contains what somebody thought of, which means the total quietly excludes everything nobody identified. Where the shape of the distribution matters as much as its centre, simulation across the range of possible outcomes tells you far more than a single averaged figure.
Finally, a point estimate hides the quality of its own inputs. Two projects can present the same £45,000 and mean entirely different things by it, one built from failure data and one built from a conversation in a corridor. The number carries none of that with it, which is why the assumptions have to travel alongside it.
Presenting an EMV so it survives the room
Show the working, not just the result. A sponsor who sees the probability, the impact range and what happens to the answer when either one moves will make a better decision and will trust the next figure you bring. State clearly what has not been converted into money, because a decision that looks marginal on cost may be straightforward once clinical disruption or a regulatory commitment is named. And be explicit that the technique compares options rather than choosing between them; where the figures land close together, the deciding factor is usually the organisation's ability to absorb a single bad outcome, which is a governance question rather than a mathematical one.
For a PMP candidate, EMV needs to be understood in two directions. The arithmetic is easy and should be quick. The recognition is harder: seeing when averaging is legitimate, when a decision tree is the clearer way to lay out the same calculation, when qualitative screening is sufficient, and when a single unaffordable outcome makes the average the wrong basis for the decision altogether. Working through those distinctions alongside contingency thinking and the wider risk techniques is a substantial part of the PMP® Exam Preparation Omega runs, where the emphasis stays on matching the technique to the decision in front of you.
On a live project, the habit worth building is smaller than the technique. When someone says a risk will probably be fine, ask two questions: probably how likely, and how expensive if not. Most of the value in expected monetary value comes from the discipline of answering those two questions out loud, before anyone reaches for a calculator.
Andre Malowney
Interested in going further?
Deciding whether to buy certainty, and knowing when an average is the wrong basis for that decision, is exactly the kind of judgement that structured preparation sharpens. Omega's PMP® Exam Preparation works through the quantitative risk techniques in the context of real project choices rather than as isolated calculations.
The PMBOK® Guide Eighth Edition sets EMV alongside the other decision and estimating techniques in its tools and techniques material, which is useful context if you want to see how it sits with decision trees and simulation.
Ad · Amazon affiliate link.
References
A162: Decision Trees Without the Headache
A163: Monte Carlo Analysis: What It Tells You and What It Doesn’t
A182: Multicriteria Decision Analysis Explained
A180: Facilitation Techniques for Difficult Project Conversations
A187: Retrospectives That Lead to Change
PMP and PMBOK are registered marks of the Project Management Institute, Inc.